If you have been wondering whether Medicare will help pay for Wegovy when heart disease enters the chat, the answer is no longer a simple yes-or-no shrug. It is more like, “Yes, sometimes, if the paperwork behaves and your diagnosis fits the rules.” That may sound deeply unromantic, but it is a big deal.
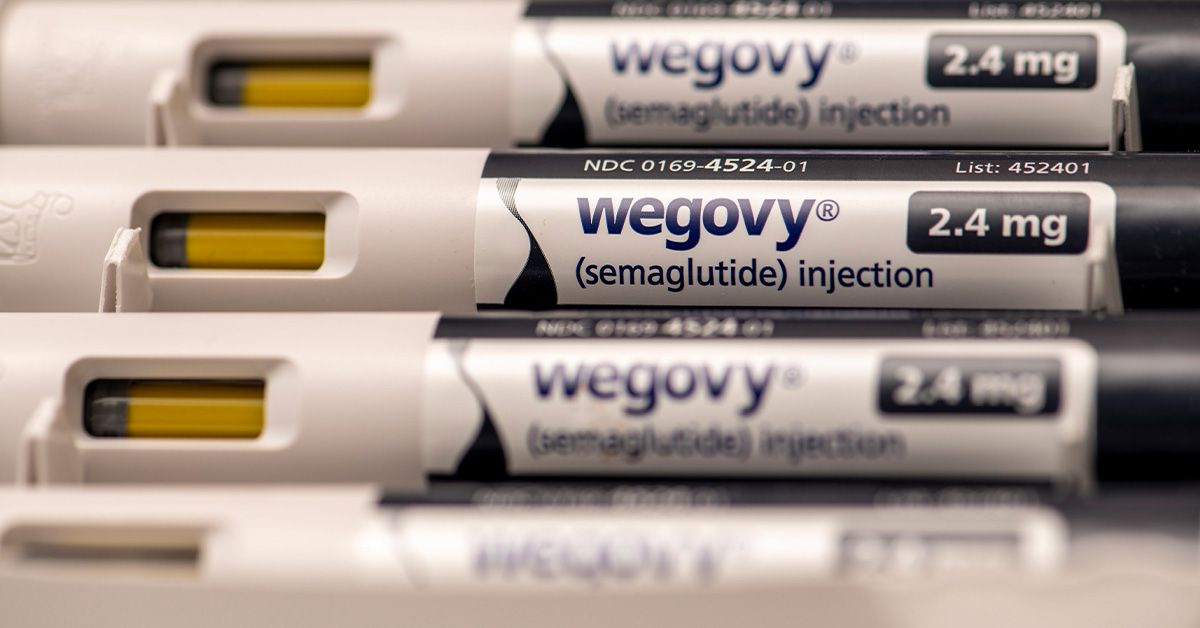
Wegovy, the brand name for semaglutide, was first known as a weight-loss medication. Then its story got more interesting. After major clinical data showed cardiovascular benefits in adults with overweight or obesity and established cardiovascular disease, Medicare Part D plans gained a path to cover it for that heart-related use. In plain English: Medicare still does not generally cover Wegovy just because someone wants help losing weight, but it may cover Wegovy when the prescription is tied to reducing the risk of major cardiovascular events in qualifying patients.
This article explains what changed, who may qualify, how Medicare coverage works, what costs may look like in 2026, and what real patients often experience when trying to get Wegovy approved. Think of it as the practical guide for people who want facts, not fluff, and maybe a tiny bit less insurance-induced eye twitching.
Why Wegovy matters in heart disease
Wegovy belongs to a class of drugs called GLP-1 receptor agonists. These medications help regulate appetite, improve satiety, and support weight reduction. That matters because obesity and overweight are strongly tied to cardiovascular risk. But the heart-disease conversation is not just about the scale anymore.
What changed the game was the evidence that semaglutide did more than help with weight loss. In the landmark SELECT trial, adults age 45 and older with overweight or obesity, established cardiovascular disease, and no diabetes had a lower risk of major adverse cardiovascular events while taking semaglutide compared with placebo. Those events included heart attack, stroke, and cardiovascular death.
That is the key reason Wegovy moved from “popular weight-loss drug” to “medication Medicare may actually cover in the right heart-disease situation.” In health policy terms, that is a plot twist. In patient terms, it can mean the difference between a rejected claim and a medically supported prescription with a fighting chance.
What the cardiovascular benefit actually means
Here is the short version without the medical confetti: Wegovy is now associated with a reduced risk of serious cardiovascular events in adults who already have established cardiovascular disease and also have obesity or overweight. That does not mean it replaces statins, blood pressure treatment, antiplatelet therapy, exercise, or smart eating habits. It means it may join that team.
Doctors are increasingly looking at semaglutide as part of cardiometabolic care rather than treating it as a vanity medication. That shift is important, because insurance coverage often follows the label, and labels follow evidence.
Does Medicare cover Wegovy for heart disease?
Yes, Medicare may cover Wegovy for heart disease-related risk reduction, but only under specific conditions. The most important distinction is this: Medicare generally does not cover anti-obesity drugs when they are prescribed only for weight loss. However, Wegovy has an FDA-approved cardiovascular indication for certain adults with established cardiovascular disease and either obesity or overweight. That opens the door to coverage under Medicare Part D.
Because Wegovy is a self-administered prescription drug, coverage usually falls under Medicare Part D or a Medicare Advantage plan with drug coverage, not Part B. So if someone has Original Medicare without Part D, this is where the record scratches. They may have Medicare, but not the part that typically handles a drug like Wegovy.
Who may qualify for Medicare coverage
A beneficiary may be a candidate for coverage if all of the following line up:
- The person is an adult enrolled in Medicare Part D or a Medicare Advantage plan with prescription drug coverage.
- The prescribing clinician documents established cardiovascular disease.
- The patient also has obesity or overweight.
- The prescription is specifically tied to the covered cardiovascular indication, not just weight loss.
- The plan’s formulary includes Wegovy and the beneficiary meets any utilization-management requirements.
What Medicare still usually will not cover
Here is the fine print that trips people up: Medicare still does not broadly cover Wegovy for obesity alone under the standard Part D benefit. So if the only diagnosis on the prescription is weight management, coverage may still be denied. The same drug can be “covered” in theory but not covered for your diagnosis. Insurance has a special talent for turning one word into a full-time obstacle.
How much could Wegovy cost with Medicare in 2026?
This is where the answer becomes maddeningly plan-specific. One beneficiary may pay a manageable copay. Another may face coinsurance, a deductible, prior authorization delays, or all three at once like an insurance-themed escape room.
In 2026, Medicare Part D includes important consumer protections. Covered prescription drug costs are capped annually, which can limit worst-case out-of-pocket spending for covered Part D drugs. That is helpful, but it does not mean Wegovy is cheap at the pharmacy counter from day one. Out-of-pocket spending depends on:
- whether Wegovy is on your plan’s formulary,
- its placement on the formulary tier,
- whether your plan deductible applies,
- whether prior authorization is approved, and
- when during the year you begin treatment.
Important 2026 cost details
For 2026, Part D plans cannot have a deductible higher than the annual Medicare limit, and total yearly out-of-pocket spending for covered Part D drugs is capped. That cap helps people using expensive medications, but only if the drug is actually covered by the plan for the approved indication.
There is also the Medicare Prescription Payment Plan, which lets beneficiaries spread out eligible out-of-pocket drug costs over the year. That may improve cash flow, but it does not reduce the total amount owed. It is a budgeting tool, not a magic wand.
Can you use manufacturer savings cards with Medicare?
Usually no. Manufacturer copay cards generally exclude people in government insurance programs, including Medicare. So the familiar “pay as little as $25” advertisements that pop up online are usually not for Medicare beneficiaries. That is not a cruel joke, but it certainly has the energy of one.
What if your income is limited?
Some beneficiaries may qualify for Medicare’s Extra Help program, which can lower Part D premiums and drug costs. If affordability is the main barrier, this is worth checking before assuming Wegovy is out of reach.
Why some Medicare plans still say “maybe” instead of “yes”
Even when a drug has a covered indication, Medicare drug plans are not required to roll out a red carpet. Coverage can vary from one plan to another because each Part D sponsor manages its own formulary and utilization rules within Medicare’s framework.
That means a plan may cover Wegovy but still require:
- Prior authorization to confirm the diagnosis and indication
- Quantity limits tied to dosing rules
- Step therapy in some circumstances
- Documentation showing established cardiovascular disease and body weight criteria
In other words, “covered” is not the same as “automatically dispensed.” A beneficiary may see Wegovy listed in a plan’s drug file and still get a denial if the plan does not receive the right medical documentation.
How to improve your chances of getting Wegovy approved
If you or a loved one is trying to access Wegovy through Medicare for heart disease, strategy matters. The strongest applications are usually boring in the best possible way: precise diagnosis, clean documentation, and no missing puzzle pieces.
1. Make sure the prescription matches the covered indication
The diagnosis should clearly support Wegovy’s cardiovascular use in an adult with established cardiovascular disease and obesity or overweight. If the chart note reads like a general weight-loss request, the plan may treat it that way.
2. Ask the doctor’s office about prior authorization before the denial arrives
Yes, that is a little like packing an umbrella because the sky looks suspicious. But it works. Many delays happen because the prescriber and the plan are technically having the same conversation in two different dialects of bureaucracy.
3. Review the formulary every year
Medicare plans change. Formularies change. Tiers change. Coverage rules change. During open enrollment, compare plans carefully if Wegovy is important to your treatment plan.
4. Appeal if appropriate
A denial is not always the end of the road. Sometimes it just means the first submission was missing documentation. If the patient truly meets the criteria, an appeal may be worthwhile.
Benefits, side effects, and safety realities
Wegovy is not a casual medication. It can be very effective, but it also comes with real side effects and safety considerations. The most common problems are gastrointestinal: nausea, vomiting, diarrhea, constipation, stomach pain, bloating, belching, indigestion, and fatigue. For many patients, the early weeks are less “miracle drug” and more “my stomach is negotiating a ceasefire.”
Gradual dose escalation is often used to improve tolerability. Even then, some people stop treatment because GI symptoms are too uncomfortable. Clinicians also watch for more serious concerns, including gallbladder issues, pancreatitis warnings, kidney problems related to dehydration, and the boxed warning related to thyroid C-cell tumors. Wegovy is not appropriate for everyone.
The upside is that the cardiovascular benefits appear meaningful for the right population. This is especially important for patients who already have heart disease and want to reduce the odds of another major event while also improving weight-related risk factors.
What the future may look like
The Wegovy-Medicare story is still evolving. Semaglutide products have been drawn into the broader Medicare pricing and access conversation, and future formulary decisions may continue to change the practical cost picture for beneficiaries. But as of now, the main rule remains clear: standard Medicare coverage hinges on a covered medical indication, not on weight loss alone.
That means Wegovy’s heart-disease indication is more than a technical label update. It is the legal and clinical bridge that made Medicare coverage possible for some beneficiaries who previously had no path at all.
Real-world experiences: what patients and families often run into
For many Medicare beneficiaries, the Wegovy journey does not begin at the pharmacy. It begins with confusion. A patient may hear on television that Wegovy “is covered by Medicare now,” call the plan, and get an answer that sounds promising. Then the prescription is denied. Suddenly, everyone involved is using the same words but meaning different things. The plan may mean the drug is on the formulary. The patient hears that as, “Great, I am approved.” The doctor may assume the cardiovascular history is obvious. The insurer may require it documented with unusual precision. That gap between assumption and documentation is where a lot of real-life frustration lives.
Another common experience is sticker shock. Even when a beneficiary expects coverage, the first quoted price can be enough to make anyone stare at the pharmacy counter like it just insulted their ancestors. Deductibles, coinsurance, and tier placement can make the first few fills feel expensive. Some people do not realize that a covered drug can still carry meaningful out-of-pocket costs until the annual cap is reached. Others find that the Medicare Prescription Payment Plan helps smooth monthly spending, even though it does not reduce the total cost.
Caregivers also end up doing a surprising amount of paperwork. Adult children may help parents compare plans during open enrollment, collect chart notes, chase prior authorization forms, and call both the cardiologist and the primary care office to make sure the diagnosis is documented correctly. It is not glamorous work, but it is often what gets treatment moving.
There is also a more hopeful side to these experiences. Some patients who qualify for Wegovy through the cardiovascular indication describe relief that their weight struggle is finally being treated as part of a broader medical picture instead of a personal failure. That shift matters emotionally. For older adults who have already had a heart attack or stroke, the conversation changes from “Will this help me fit into smaller pants?” to “Will this help me avoid another major event and stay independent longer?” That is a very different and much more serious question.
Patients also describe mixed experiences with side effects. Some tolerate the medication well after dose escalation. Others find the nausea, constipation, or stomach discomfort so disruptive that they reconsider treatment. The real-world story is not a fairytale and not a disaster either. It is usually a careful balancing act between benefit, tolerability, cost, and access.
And then there is the annual plan-check ritual. Beneficiaries who successfully get coverage one year often learn not to get too comfortable. Formularies can change. Authorization rules can tighten. Pharmacies can tell a different story than the online plan finder. So experienced patients become part health consumer, part insurance detective, and part administrative ninja. It is not the hobby anyone asked for, but it is often how people keep access to the therapies that matter.
Conclusion
Wegovy and Medicare coverage for heart disease now sit at the intersection of science, policy, and paperwork. The science says semaglutide can reduce cardiovascular risk in certain adults with established cardiovascular disease and overweight or obesity. The policy says Medicare may cover it under Part D for that approved indication. The paperwork says, “Please prove all of that, neatly, and maybe twice.”
For patients who qualify, that coverage pathway is meaningful. It does not guarantee easy access, low costs, or instant approval. But it does mean Wegovy is no longer boxed into the “weight-loss only” category for Medicare purposes. That is a major shift.
If you are considering Wegovy through Medicare, the smartest move is to treat coverage like part of the care plan. Confirm the diagnosis, verify the formulary, prepare for prior authorization, and review plan options every year. In the world of Medicare and specialty medications, optimism is helpful, but documentation is the real love language.
This article is for educational purposes only and should not replace personalized medical or insurance advice from a licensed clinician, pharmacist, or Medicare counselor.