Animal Spirits Episode 51: The Healthy Correction is one of those investing podcast episodes that sounds like it was recorded with one eye on a blinking market screen and the other on a stack of very human financial problems. Hosted by Ben Carlson and Michael Batnick, the episode arrived in October 2018, a moment when investors were being reminded that stocks do not always move up and to the right like a motivational poster in a brokerage office.
The phrase “healthy correction” may sound strange. After all, most people do not describe falling account balances as healthy. Nobody opens a 401(k), sees red numbers, and says, “Wonderful, my portfolio is doing cardio.” But in markets, corrections can serve a purpose. They cool down overconfidence, reset valuations, expose weak assumptions, and remind investors that risk is not a typo buried in the fine print.
This episode matters because it does not treat a market selloff as a single scary headline. Instead, it connects the dots between stock market volatility, retirement behavior, household debt, business disruption, indexing, health care savings, and investor psychology. In other words, it is not just about the market having a rough week. It is about how people react when money, fear, ambition, and uncertainty all walk into the same room.
What Is Animal Spirits Episode 51 About?
At its core, Animal Spirits Episode 51: The Healthy Correction is a wide-ranging conversation about markets and life during a period of renewed volatility. The episode discusses recent market turbulence, whether 401(k) investors might act as a stabilizing force, the risks of 401(k) loans, the collapse of Sears, student loan debt, first-time homebuyers, index investing, Tesla, HSAs, and the psychology of holding a 100% stock portfolio.
That may sound like a lot, because it is. Animal Spirits is not the kind of finance show that spends an hour whispering lovingly to a discounted cash flow model. The strength of the podcast is that it treats investing as part of everyday life. The stock market is connected to jobs. Jobs are connected to retirement plans. Retirement plans are connected to household behavior. Household behavior is connected to debt, housing, health care, and confidence.
The title “The Healthy Correction” points to the market backdrop. A correction is generally understood as a decline of at least 10% from recent highs. It feels uncomfortable, but it is not automatically a disaster. Corrections can be part of a normal market cycle, especially after strong returns, stretched expectations, or a period when investors have become too comfortable.
Why a Market Correction Can Be Healthy
A healthy correction does not mean every decline is good news. It means that not every decline is a crisis. Markets occasionally need to breathe, even if the breathing sounds like a crowded theater gasping at once.
In 2018, investors were dealing with rising interest rates, trade tensions, technology stock weakness, and questions about whether the long post-financial-crisis bull market was getting tired. Volatility returned after a long period in which many investors had become used to calm markets. The danger of calm markets is that they can train people to confuse stability with safety.
Corrections can reset expectations in several useful ways. First, they remind investors that stocks are risky assets. Second, they create better entry points for long-term buyers. Third, they reveal which investors had a plan and which investors were simply borrowing courage from rising prices. Fourth, they separate durable businesses from popular stories. When everything is going up, every idea looks smart. When prices fall, the market suddenly becomes a much stricter teacher.
The Difference Between Volatility and Permanent Loss
One of the most useful lessons from the episode is the difference between volatility and permanent loss. A broad market index can fall sharply and recover over time. A poorly run company, however, can decline and never return. That distinction matters because investors often treat every red number the same way. They panic over a diversified portfolio decline while giving endless patience to a single stock with deteriorating fundamentals.
A correction in the stock market can be temporary. A broken business model can be permanent. That is why diversification, asset allocation, and realistic expectations matter so much.
401(k) Plans: A Market Floor or a Behavioral Trap?
One of the interesting questions in the episode is whether 401(k) contributions help provide a floor under the market. The theory is simple: millions of workers contribute to retirement accounts automatically every paycheck. Those contributions keep buying stocks through index funds, target-date funds, and mutual funds. In theory, this steady buying might soften downturns.
But the episode wisely complicates that idea. Automatic contributions are powerful, but investors are still human. People can reduce contributions, take loans, cash out accounts after changing jobs, or panic during severe downturns. The 401(k) system is one of the most important wealth-building tools in America, but it depends on behavior as much as design.
The Problem With 401(k) Loans
401(k) loans are tempting because they allow workers to borrow from themselves. The interest rate may look reasonable, and the process can feel less intimidating than dealing with a bank. But the risks are real. When workers leave a job with an outstanding loan, repayment can become difficult. If the loan is not repaid properly, it can turn into a taxable withdrawal, often with penalties for younger workers.
The deeper issue is opportunity cost. Money removed from a retirement account is money that is no longer compounding. A small decision made during a cash crunch can echo for decades. That is the kind of financial problem that does not arrive wearing a villain costume. It arrives looking practical.
Sears, Amazon, and the Danger of Missing the Future
Animal Spirits Episode 51 also discusses the fall of Sears, which had filed for bankruptcy in October 2018. Sears was not just another retailer. It was once a dominant American institution, famous for catalogs, nationwide stores, private-label brands, and a role in reshaping how Americans shopped.
The Sears story is fascinating because it mirrors parts of the Amazon story. Sears used catalogs and logistics to reach customers who lacked access to big-city stores. Amazon used the internet and logistics to reach nearly everyone. In its prime, Sears was a retail innovator. By 2018, it had become a warning sign.
The lesson is not simply “Amazon killed Sears.” That explanation is too easy and, frankly, a little lazy. Sears struggled with strategic mistakes, underinvestment, financial engineering, competition from Walmart and Target, changing consumer expectations, and a failure to modernize the customer experience. Amazon accelerated the pressure, but Sears had been weakening for years.
What Investors Can Learn From Sears
Sears teaches investors that famous brands are not automatically safe investments. A company can have history, nostalgia, and name recognition and still fail to adapt. The market does not award lifetime achievement trophies. It rewards future cash flows, competitive advantage, execution, and relevance.
This is where the episode’s broader point about individual stocks versus the stock market becomes important. The stock market can survive the decline of once-great companies because indexes evolve. Weak firms shrink or disappear, while stronger companies take their place. Individual stock investors do not get that benefit unless they build it into their own process.
Student Loans and the First-Time Homebuyer Squeeze
The episode also highlights student loan debt and its impact on the economy, especially first-time homebuyers. In 2018, outstanding student loan balances were already above $1.5 trillion. That debt burden affected more than monthly budgets. It influenced life decisions: buying a home, starting a family, changing jobs, saving for retirement, and building emergency funds.
Student loans are not only a personal finance issue. They are a macroeconomic issue because they shape household formation and consumer behavior. If younger adults delay buying homes because debt payments consume income, the effects ripple through real estate, construction, furniture, appliances, insurance, and local economies.
The Down Payment Problem
For many aspiring homeowners, the biggest challenge is not understanding mortgage math. It is saving the down payment while rent, health care, transportation, food, and student loans all line up at the paycheck like they bought VIP tickets. High student loan payments can make it harder to save consistently, even for people with decent incomes.
This ties back to the episode’s broader message: markets are not separate from real life. Portfolio returns matter, but so do debt payments, wages, housing costs, job mobility, and financial habits.
Index Investing and the Question of Market Health
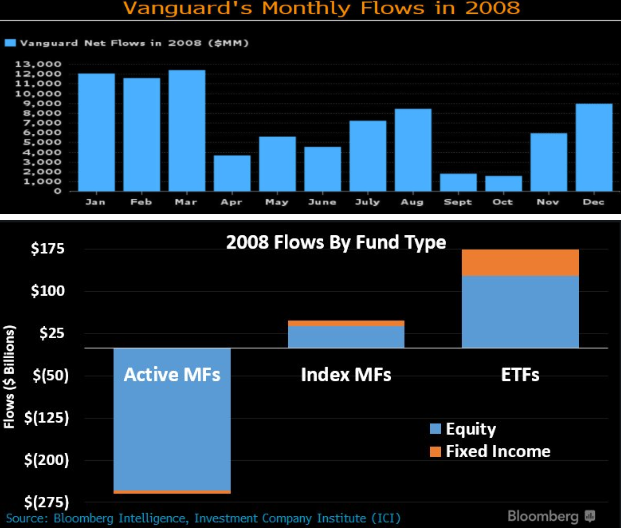
Another major topic in Animal Spirits Episode 51 is index investing. By 2018, indexing had already transformed the investment industry. Low-cost index funds and ETFs gave ordinary investors access to diversified portfolios at prices that would have seemed almost magical decades earlier.
Critics worry that too much indexing could distort markets, reduce price discovery, or concentrate voting power. Supporters argue that indexing lowers costs, improves diversification, and helps investors avoid the expensive mistakes that often come from trying to outsmart everyone else.
The practical answer is less dramatic than the debate. Index investing is not perfect, but for many people it is a very useful tool. It offers broad exposure, low fees, transparency, and simplicity. The danger is not that investors use index funds. The danger is that investors use them without understanding what they own, how concentrated certain indexes can become, or how they might behave during a downturn.
Passive Does Not Mean Emotionless
One of the funniest myths in finance is that passive investors are passive people. A person can own an index fund and still panic like a squirrel in a leaf blower. The fund may be passive, but the owner still has feelings, headlines, group chats, and a brokerage password.
Successful indexing requires discipline. It asks investors to accept market returns, rebalance when needed, and resist the urge to turn every scary headline into a portfolio makeover.
Tesla, Hype, and the Difference Between a Stock and a Story
The episode also touches on Tesla and the question of whether it had outsold Mercedes-Benz. Tesla was one of the defining market stories of the late 2010s: part car company, part technology company, part belief system, and part internet argument generator.
Tesla is a useful case study because it shows how investors can become attached to narratives. A great company can still have a volatile stock. A controversial CEO can still lead a disruptive business. A powerful product cycle can still be difficult to value. The market often struggles when a company does not fit neatly into an old category.
That is why the episode’s discussion of individual stocks versus the stock market is so valuable. The stock market is a collection of businesses, but owning one exciting company is not the same as owning the market. Individual stocks can deliver huge gains, but they can also deliver sleepless nights, sharp drawdowns, and enough message-board drama to make a soap opera look emotionally balanced.
HSAs: The Underrated Personal Finance Tool
Health Savings Accounts, or HSAs, also come up in the episode. HSAs are often underappreciated because they sound boring. That is unfortunate because boring is sometimes where the financial magic hides. An HSA can offer tax advantages when used for qualified medical expenses, and unused balances can roll over from year to year.
For eligible people, HSAs can play a unique role. They can help cover current medical expenses, support emergency planning, and potentially become part of a long-term retirement health care strategy. The challenge is that many households are already stretched. Telling someone to maximize an HSA while they are juggling rent, student loans, child care, and groceries can sound like telling a person on a treadmill to also learn the violin.
Still, the topic belongs in the episode because health care costs are one of the biggest financial uncertainties households face. A portfolio is not truly healthy if it ignores the real expenses people are likely to encounter.
The Psychology of a 100% Stock Portfolio
One of the most important parts of the episode is the psychology behind a 100% stock market portfolio. On a spreadsheet, a 100% stock allocation can look rational for long-term investors with high risk tolerance. Over long periods, stocks have historically offered strong returns compared with safer assets. But spreadsheets do not wake up at 3 a.m. wondering whether the global economy is falling apart.
The real question is not whether a 100% stock portfolio can work mathematically. It is whether the investor can stick with it emotionally. A strategy that looks optimal but gets abandoned at the worst moment is not optimal. It is a trap wearing a nice suit.
Risk Tolerance Is Discovered, Not Declared
Many investors think they have high risk tolerance during bull markets. That is like saying you are a great sailor while standing on a dock in perfect weather. Risk tolerance is revealed during drawdowns, recessions, job losses, and moments when everyone suddenly becomes an expert in doom.
The healthiest portfolio is not always the one with the highest expected return. It is the one the investor can hold through bad markets without making destructive decisions. For some people, that means more bonds. For others, it means more cash. For others, it means automated contributions and fewer market updates. The best plan is the one that survives contact with your actual personality.
Why This Episode Still Feels Relevant
Although Animal Spirits Episode 51 was recorded in 2018, its themes remain relevant because investor behavior has not received a software update. People still panic during corrections. They still chase popular stocks. They still underestimate debt. They still love simple narratives. They still forget that great companies can become weak companies and boring habits can create serious wealth.
The episode also shows why financial media works best when it connects markets to human behavior. A market correction is not just a chart pattern. It is a test of planning, expectations, liquidity, and emotional control. A retirement account is not just a balance. It is a future claim on freedom. A student loan is not just a line item. It can shape major life choices. A company like Sears is not just a bankruptcy case. It is a reminder that disruption eventually visits everyone.
Experiences Related to Animal Spirits Episode 51: The Healthy Correction
Listening to or reflecting on Animal Spirits Episode 51: The Healthy Correction feels a lot like sitting through a practical investing class where the professor occasionally throws in a joke so everyone remembers to breathe. The episode captures the emotional reality of investing better than many formal market reports. It reminds us that the hardest part of investing is rarely finding information. The hard part is behaving well after finding too much information.
One common experience related to this topic is watching a portfolio decline for the first time after becoming serious about investing. During a bull market, investing can feel easy. Contributions go in, balances rise, and everyone feels like a disciplined long-term thinker. Then the market drops. Suddenly, the same person who proudly said “I’m investing for 30 years” is checking their account six times before lunch. Nothing exposes the gap between theory and reality like a correction.
A healthy correction can teach humility. It forces investors to ask better questions. Do I actually understand what I own? Is my emergency fund large enough? Am I taking more risk than I admitted? Did I buy this stock because of research or because someone on the internet used rocket emojis? These questions are not always comfortable, but they are useful.
Another experience tied to the episode is the realization that personal finance and investing cannot be separated. A person with high-interest debt, no emergency fund, unstable income, and a 100% stock portfolio may not be aggressive. They may simply be fragile. On the other hand, a person with steady savings, low debt, insurance coverage, and a diversified portfolio may be able to tolerate volatility without panic. The portfolio is only one part of the household balance sheet.
The discussion of 401(k) loans is especially relatable. Many workers do not borrow from retirement plans because they are reckless. They borrow because life is expensive and emergencies do not wait politely for payday. A car breaks. A medical bill arrives. Rent increases. A family member needs help. The lesson is not to shame people for difficult choices. The lesson is to build systems that reduce the need for costly trade-offs. Emergency savings, realistic budgets, and better financial education can all help.
The Sears discussion also offers a real-world experience for anyone who has watched a familiar brand fade. Many people grew up with Sears as a household name. Seeing it decline was a reminder that nostalgia is not a strategy. Investors can learn from this by being careful with “it has always been around” thinking. The market does not care how long a company has existed if customers move on.
The episode’s point about Tesla and individual stocks also resonates with modern investors. Owning a disruptive company can be thrilling, but thrill is not the same as a plan. A single stock can make an investor feel brilliant one year and foolish the next. That does not mean individual stocks are bad. It means position sizing, diversification, and humility matter.
Finally, the phrase “healthy correction” is useful beyond markets. Careers have corrections. Spending habits have corrections. Business models have corrections. Even personal goals sometimes need corrections. A setback can be painful and still useful if it reveals a weak spot before the damage becomes permanent. That is the lasting experience from Animal Spirits Episode 51: volatility is not the enemy. Lack of preparation is.
Conclusion
Animal Spirits Episode 51: The Healthy Correction remains a valuable episode because it treats investing as a living, breathing human activity. It is not only about market prices. It is about behavior, debt, retirement systems, business change, health care costs, and the stories investors tell themselves when markets get noisy.
The key takeaway is simple: corrections are uncomfortable, but they can be useful. They test assumptions, reveal weaknesses, and reward investors who prepared before the storm. A healthy correction does not feel healthy while it is happening. It feels annoying, scary, and rude. But for long-term investors, it can be the market’s way of saying, “Check your plan before you need it most.”